Bitcoin Is Easy to Buy. Capital Is Harder to Govern.
Bitcoin Is Easy to Buy. Capital Is Harder to Govern.
Daily Perspective
Bitcoin treasury companies are discovering an inconvenient truth.
Buying Bitcoin is not the difficult part.
The difficult part is repeatedly finding capital, deciding which stakeholders absorb the cost, and ensuring that the financing structure does not eventually force the company to undo the very strategy it was created to pursue.
Capital B just raised €21 million through a private share placement to expand its Bitcoin treasury. Meanwhile, Genius Group is trying to rebuild a Bitcoin position after previously selling its holdings to address debt.
Same asset.
Very different capital stories.
The market still loves the headline number. Treasury v2 cares about what happened to the balance sheet to create it.
1. Capital B raises €21 million to expand its Bitcoin holdings
Capital B raised approximately €21 million through a private share placement involving institutional investors, including strategic Bitcoin investors, with proceeds intended to support continued treasury expansion.
The interesting number is not €21 million.
It is the financing mechanism.
Issuing equity to acquire Bitcoin can increase corporate BTC holdings while simultaneously increasing the denominator over which those holdings are economically distributed.
Treasury governance question: Did the transaction increase Bitcoin exposure for existing shareholders, or simply increase the company's Bitcoin inventory?
Those are not the same thing.
2. Genius Group wants to rebuild the Bitcoin treasury it previously had to sell
Genius Group reportedly plans to rebuild a Bitcoin treasury after selling its earlier holdings to help satisfy debt obligations.
That deserves more attention than another acquisition announcement.
A Bitcoin treasury strategy that can be interrupted by ordinary corporate financing pressure is not merely exposed to Bitcoin volatility. It is exposed to the company's liabilities, creditors, liquidity requirements, refinancing options, and operating cash needs.
The Bitcoin did not fail.
The capital structure made the decision.
That distinction is becoming rather important.
3. Bitcoin demand is strengthening again as ETFs attract capital
ETF inflows and improving liquidity expectations have helped Bitcoin regain momentum, with macro developments around U.S. Treasury bond purchases contributing to renewed demand.
That is encouraging for anyone holding Bitcoin.
It is less useful as a governance strategy.
A favorable liquidity environment can improve valuations, reopen capital markets, and make treasury financing easier. It can also make questionable structures look healthier than they really are.
Bull markets have performed this particular magic trick before.
4. Jackson Hole becomes the next macro test
Markets are watching Federal Reserve Chair Kevin Warsh's Jackson Hole remarks for clues about monetary policy, Treasury-market conditions, and the broader liquidity environment supporting Bitcoin and other hard assets.
For treasury operators, the important question is not whether the speech sends Bitcoin up or down Monday morning.
It is whether the treasury strategy remains viable under either outcome.
If the financing model requires friendly rates, abundant liquidity, and a rising BTC price simultaneously, the strategy is not resilient.
It is conditional.
What This Actually Means
Bitcoin treasury companies are increasingly becoming capital-allocation businesses, not simply Bitcoin holders.
That changes the analytical question.
Treasury v1 asks:
How much Bitcoin did they buy?
Treasury v2 asks:
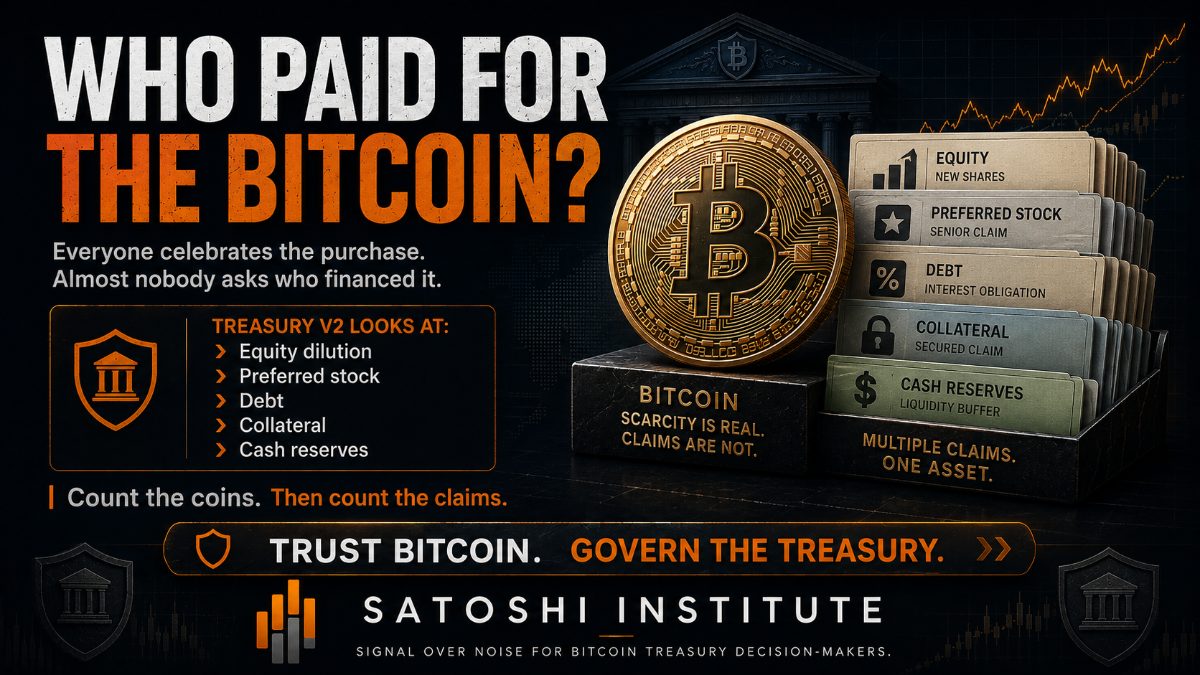
What did they have to issue, pledge, refinance, dilute, reserve, or surrender to buy it?
Consider the contrast.
- Capital B can raise new equity and purchase additional Bitcoin.
- Genius Group can sell Bitcoin when debt pressure demands liquidity.
Another company can issue preferred shares.
Another can issue converts.
Another can create a cash reserve.
Another can pledge Bitcoin as collateral.
All of them can truthfully announce that Bitcoin is central to their strategy.
Yet their shareholders may be assuming dramatically different risks.
This is why raw BTC holdings are becoming a less useful standalone measure of treasury quality.
The numerator tells you what the company owns.
The denominator, liabilities, liquidity requirements, and financing obligations tell you who actually benefits from it.