The Buyers Are Back. So Are the Sellers.
The Buyers Are Back. So Are the Sellers.
Daily Perspective
For a few days, the Bitcoin treasury world can enjoy something familiar again.
Strategy is buying. Strive is buying. Bitcoin is near $78,000. The accumulation charts are moving in the preferred direction.
Order has apparently been restored to the universe.
Except Hyperscale Data sold roughly 65 BTC during the same period. That matters more than it might appear. One treasury saw conditions that supported adding Bitcoin. Another saw conditions that supported converting Bitcoin into roughly $5.1 million of cash.
Same asset. Same market. Different balance sheets. And that is the distinction Bitcoin treasury analysis increasingly has to understand.
Bitcoin may be unconditional. Corporate Bitcoin never is.
The Satoshi Institute newsletter exists as a governance signal filter rather than a price digest, with each issue explicitly meant to ask what current events teach us about Bitcoin treasury governance.
The Day’s Signals
1. Strategy Is Buying Again
Strategy returned to the market after its summer hiatus, purchasing 4,603 BTC for approximately $369.7 million, at an average price around $80,318 per Bitcoin.
Its holdings rose to roughly 845,050 BTC.
The obvious interpretation is: The accumulation machine is running again.
The more useful interpretation is that Strategy apparently believes its current liquidity, financing capacity and capital structure again permit additional Bitcoin purchases.
That distinction matters. The purchase is not merely a statement about Bitcoin. It is a statement about what Strategy's balance sheet currently allows Strategy to do.
Signal
Treasury capacity determines accumulation capacity. Bitcoin conviction may be permanent. The ability to act on that conviction is not.
2. Strive Is Buying Too
Strive reportedly purchased another 1,800 BTC for approximately $143 million, paying an average of roughly $79,431 per Bitcoin.
That brought its reported holdings to approximately 23,156 BTC.
With multiple treasury companies returning to accumulation, the temptation will be to declare the corporate Bitcoin trade fully restored.
Perhaps.
But Treasury v2 asks a different question:
What financed the purchase, and what happened to the economics of the common shareholder in the process?
Coin count is easy to report. Capital efficiency is harder.
Signal
A treasury should not receive governance credit merely because BTC holdings increased.
The question is whether Bitcoin exposure per economically relevant share improved without creating disproportionate financing risk.
3. Hyperscale Data Did the Opposite
While Strategy and Strive were adding Bitcoin, Hyperscale Data reported selling approximately 65 BTC for about $5.1 million during the week ended August 30.
Its remaining treasury reportedly stood around 214.97 BTC, worth approximately $16.7 million.
This may be today's most useful story. Not because selling Bitcoin is inherently good or bad. Because it demonstrates that corporate Bitcoin exists inside a larger system of obligations.
- Cash requirements.
- Capital expenditures.
- Debt.
- Operating needs.
- Financing conditions.
- Board decisions.
- Shareholder expectations.
The Bitcoin did not suddenly become less scarce because the company sold it. The company's priorities changed.
Signal
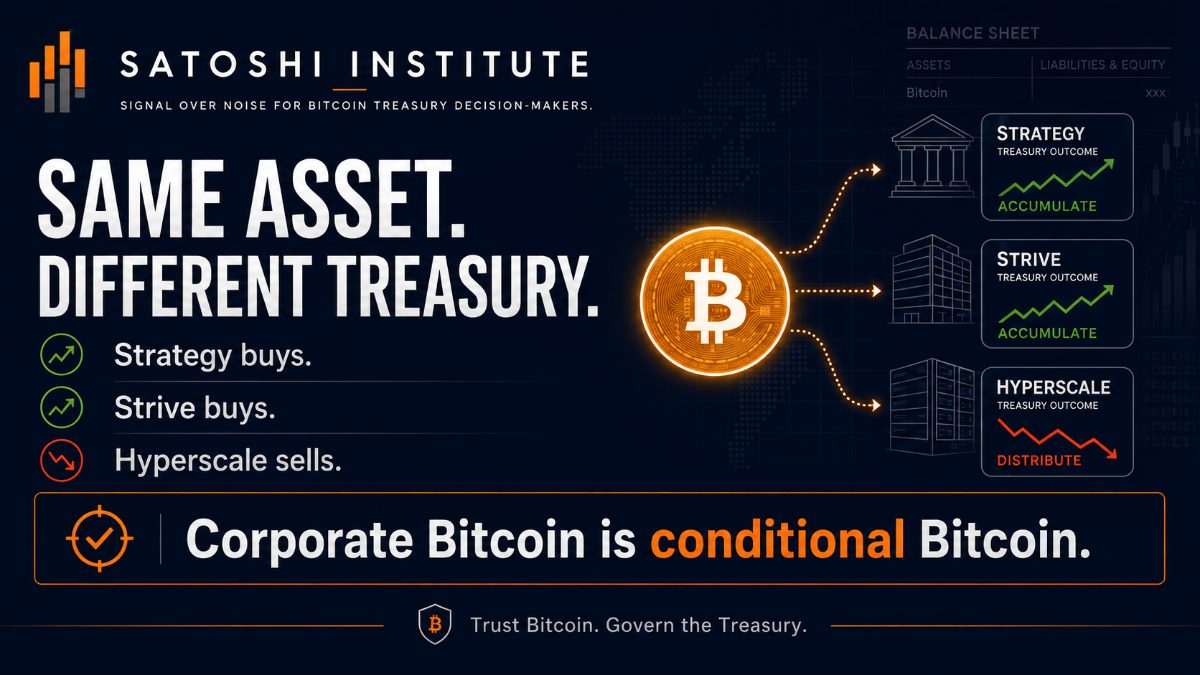
Corporate Bitcoin is conditional Bitcoin.
It remains on the balance sheet only while the economics of the enterprise allow it to remain there.
4. The Treasury Shakeout Is Becoming Visible
Reports increasingly describe a divergence among Bitcoin treasury companies.
Some are buying again. Others are retreating. Some are experimenting with options, collars and secured lending. Others are attempting to rebuild treasuries after having previously sold Bitcoin to satisfy other obligations.
This is what institutionalization looks like. Not permanent accumulation.
Different capital structures producing different decisions under the same market conditions.
The Treasury v1 narrative tended to treat every corporate Bitcoin purchase as broadly equivalent.
Treasury v2 cannot.
A company holding unencumbered BTC financed with durable equity is not economically identical to a company holding BTC against debt, preferred obligations, collars, liquidity requirements or operating cash deficits.
The coins may look identical on-chain. The claims surrounding them are not.
Signal
The next generation of treasury analysis must measure encumbrance, liquidity dependency and financing structure, not simply Bitcoin quantity.
What This Actually Means
A very useful market experiment is unfolding in front of us.
Strategy buys. Strive buys. Hyperscale sells.
That appears contradictory only if we assume Bitcoin is the strategy.
It is not. Bitcoin is the asset. The treasury strategy is the system surrounding it. That system determines whether management can continue accumulating when BTC falls 30%.
- Whether debt can be serviced without touching the Bitcoin.
- Whether preferred dividends can be funded.
- Whether dilution remains economically accretive.
- Whether pledged Bitcoin can remain unencumbered.
- Whether operating cash requirements eventually compete with treasury objectives.
- And whether the board has already decided what happens when those priorities collide.
This is why simple corporate Bitcoin rankings based solely on BTC holdings are becoming progressively less informative. Two companies may each hold 10,000 BTC. One may effectively control all 10,000. The other may economically control considerably less once debt claims, options, liquidity requirements and financing obligations are considered.
On a dashboard they look similar. Under stress they may behave very differently. And stress is where treasury design stops being theoretical.