Preferred Stock Is Becoming the Bitcoin Treasury Infrastructure
Preferred Stock Is Becoming the Bitcoin Treasury Infrastructure
Perspective
The Bitcoin treasury market may have found its next operating system.
Not common equity. Not convertible debt.
Preferred stock.
Strive has now closed an upsized $630 million SATS preferred offering carrying a 15% fixed annual dividend, with the security beginning to trade on Nasdaq. Strategy continues to manage and repurchase STRC while expanding its digital-credit repurchase authorization to $3 billion. Metaplanet, meanwhile, is using the pending Superplanet transaction to establish a U.S. capital-markets platform that could eventually support its own dollar-denominated preferred issuance. Strive
That is a meaningful shift.
The first generation of the treasury model depended heavily on common equity trading above NAV. When that premium existed, the arithmetic could be remarkably attractive: issue expensive equity, buy scarce Bitcoin, and potentially improve BTC per share.
That trade becomes much harder when mNAV approaches 1x.
Preferreds offer another route.
They protect the common-share denominator from immediate dilution and potentially keep the Bitcoin acquisition engine running.
But they also transform the treasury company into something much more complicated.
The central question is no longer simply whether Bitcoin goes up.
It is whether the capital stack works through the entire cycle.
Signals
1. Strive just turned SATS from an experiment into a real capital market
Strive originally proposed 5 million SATS shares. Demand allowed it to upsize the offering to 7 million shares at $90, generating approximately $630 million gross. SATS carries a fixed 15% annualized cumulative dividend, paid every business day when declared, and ranks below SATA but above Strive common equity. Strive
That matters more than Strive moving up another place in the Bitcoin rankings. The company has demonstrated that investors are willing to provide hundreds of millions of dollars of preferred capital to a Bitcoin treasury company even at a substantial required yield.
For Strive, the benefit is obvious: another pool of capital that does not immediately expand the ASST common-share count.
For SATS investors, the proposition is very different. They are exchanging much of the common equity's Bitcoin upside for a large recurring claim on the company.
The treasury now has another financing engine. It also has another obligation.
2. Strategy is increasingly managing digital credit as a business of its own
Strategy added another 267 BTC, bringing reported holdings to 848,517 BTC.
But again, the Bitcoin purchase was not the largest capital move.
Strategy repurchased approximately $193 million of STRC and increased its Digital Credit Securities Repurchase Program from $2 billion to $3 billion. It also reported roughly $5.3 billion of USD assets available within its broader capital framework. Strategy
That makes the evolution increasingly obvious. Strategy is no longer simply issuing securities because it wants more Bitcoin. It is actively managing an ecosystem of securities around the Bitcoin.
- Issue when capital is attractive.
- Repurchase when the security is dislocated.
- Maintain liquidity.
- Protect funding channels.
- Acquire Bitcoin when the economics justify it.
The treasury is becoming a capital-markets platform.
3. Metaplanet is building a U.S. bridge for the same playbook
Super League shareholders have approved the transaction under which Metaplanet will contribute 2,100 BTC plus $2.5 million in cash to the company, which is expected to become Superplanet and trade under the ticker SUPA after closing. Metaplanet will receive a controlling position, and the structure gives it a Nasdaq-based platform alongside its Tokyo listing. SEC
The 2,100 BTC is important.
The U.S. capital-market access may prove more important.
Metaplanet has already demonstrated that it wants to move beyond the original accumulation model. A U.S. platform creates another potential route to dollar funding, structured securities and, eventually, the kind of preferred-capital architecture Strategy and Strive are developing.
That would make preferred financing less of a Strategy innovation and more of an emerging industry standard.
What It Means
The next stage of Bitcoin treasury competition may not be determined by who can raise the most equity.
It may be determined by who can build the deepest, cheapest and most resilient capital stack around Bitcoin.
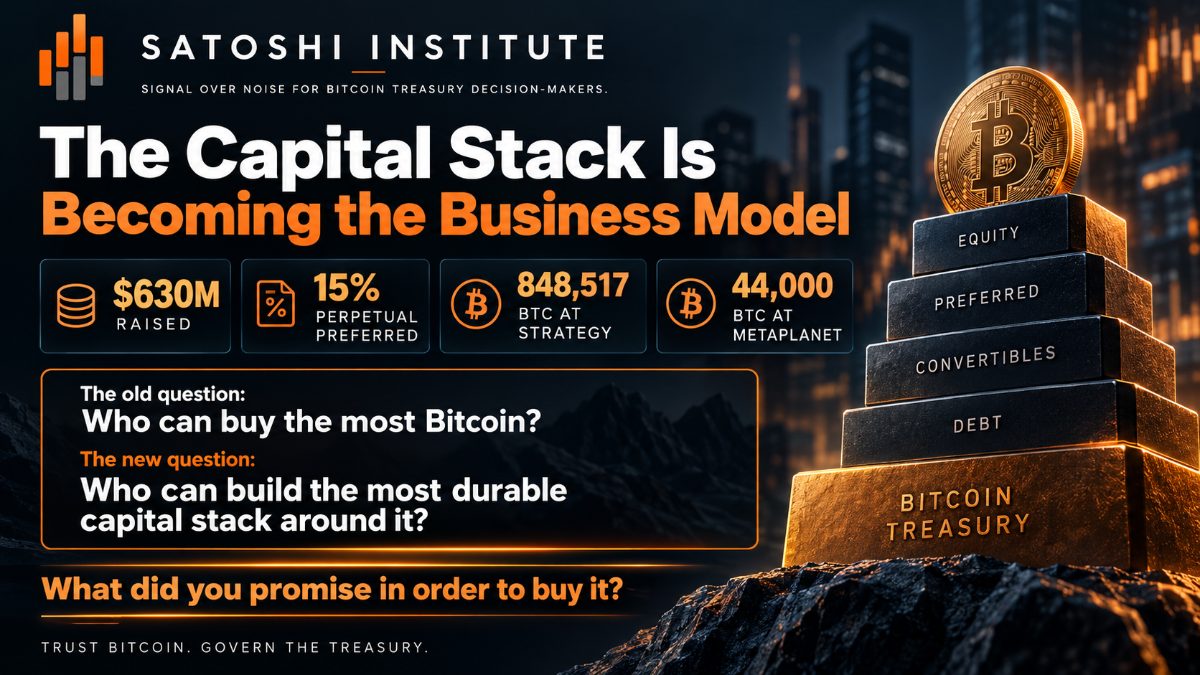
Strive has now shown that investors will buy 15% perpetual preferred capital at scale. Strategy is showing what active management of that type of security can look like. Metaplanet is creating a U.S. platform that could give it access to the same financing ecosystem.
That opens a much larger capital pool. It also raises the standard considerably.
A company issuing perpetual preferred stock must now manage not only Bitcoin volatility, but dividend coverage, seniority, liquidity, repurchases and the relationship between fixed claims and common-share economics.
Preferred stock may solve the dilution problem. It does not solve the governance problem.
The defining question of this phase will therefore not be: How much Bitcoin did you buy?
It will be: What did you promise in order to buy it, and can that promise survive a full cycle?
Bitcoin is the reserve asset.
The capital stack is becoming the business model.