Strategy Is Buying Again. The Balance Sheet Still Keeps Score.
Strategy Is Buying Again. The Balance Sheet Still Keeps Score.
Why Today Matters
Strategy is back in the market.
After pausing purchases since late June, the company acquired 4,603 BTC for roughly $370 million, bringing reported holdings to 845,050 BTC.
That will dominate the headlines. “Strategy is so back” is certainly easier to fit on a T-shirt.
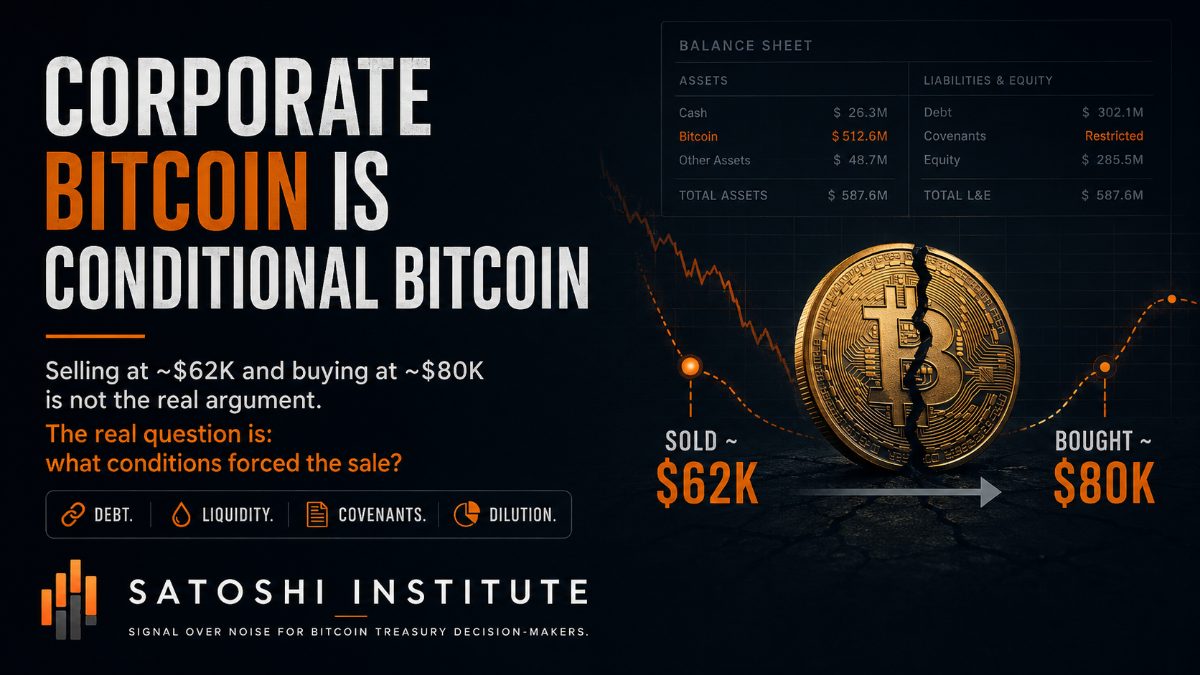
But treasury governance requires remembering what happened before the comeback. Strategy reportedly sold 6,948 BTC between May and August at roughly $62,250 per coin, then returned to the market at an average price of about $80,318.
Bitcoin accumulation has resumed.
The capital-allocation record did not reset with it.
Signals We’re Watching
Market Signals
What capital and treasury behavior are telling us
Observed
- Strategy purchased 4,603 BTC for approximately $369.7 million, its first acquisition since late June.
- The purchase price averaged about $80,318 per BTC.
- Earlier sales reportedly occurred around $62,250 per BTC, meaning the company returned to the market at materially higher prices.
- Strive also continued accumulating, reportedly adding another 1,800 BTC while its equity substantially outperformed several other Bitcoin-linked names during August.
Signal
The market is returning to accumulation mode, but accumulation volume tells us surprisingly little about the quality of the treasury strategy.
A company can own more Bitcoin while simultaneously making less-efficient capital-allocation decisions.
That distinction becomes increasingly important as Bitcoin treasury companies mature.
Policy Signals
What the macro environment is telling us
Observed
Treasury-market conditions remain an important part of Bitcoin’s current backdrop. Long-duration U.S. yields remain elevated, while Treasury buyback activity and expectations around liquidity continue influencing risk assets.
Stablecoin growth is also creating additional demand for short-duration Treasury bills. That strengthens the connection between crypto markets and traditional dollar funding markets without necessarily solving pressure farther out on the yield curve.
Signal
Bitcoin treasury companies are not operating outside the financial system anymore.
They are becoming increasingly sensitive to it. Interest rates influence financing costs. Bond markets influence liquidity. Equity markets influence issuance capacity. Preferred securities create additional claims.
Macro conditions can therefore determine whether a treasury company is accumulating Bitcoin, raising capital, pledging assets, or selling Bitcoin.
That is why a Bitcoin treasury cannot be governed as though Bitcoin were the only variable.
Security & Structural Risk Signals
What hidden claims on Bitcoin are telling us
Observed
Several smaller treasury companies are demonstrating how quickly straightforward Bitcoin ownership can become something considerably more complicated.
PowerCompute reportedly used a collar structure involving 307 BTC, with an early reset adding approximately $3.8 million of debt.
Other treasury structures highlighted in recent reporting include secured loans, options positions, large resale registrations, and derivatives tied directly to corporate crypto holdings.
Signal
A corporate disclosure saying “we own X Bitcoin” increasingly tells investors only the beginning of the story.
The next questions are:
- How much is pledged?
- How much is hedged?
- How much supports debt?
- How much is subject to options?
- What counterparties have claims?
- What happens when collateral thresholds move?
Treasury v2 treats those questions as part of the Bitcoin position itself.
What This Actually Means
There is an important psychological reset taking place. For several months, the Bitcoin treasury conversation was forced to discuss liquidity, capital preservation, debt, financing structures, and even sales.
Now Bitcoin has rallied and Strategy is buying again.
The temptation will be to declare the unpleasant part over.
It probably is not.
Strategy's latest purchase actually demonstrates why the unpleasant part mattered.
Selling Bitcoin at roughly $62,000 and later buying Bitcoin around $80,000 is not an argument against Strategy. It is an illustration of something much more important:
Corporate Bitcoin is conditional Bitcoin.
A Bitcoin holder can simply hold.
A corporation has payroll.
Debt.
Preferred dividends.
Capital requirements.
Shareholders.
Counterparties.
Liquidity needs.
Boards.
And occasionally markets that stop cooperating.
That means the question is never merely:
How much Bitcoin does the company own?
The institutional question is:
Under what conditions can the company continue owning it?
That is the dividing line between accumulation and treasury management.