Bitcoin Is Recovering. Trust Is Not.
Bitcoin Is Recovering. Trust Is Not.
Daily Perspective
Bitcoin can rally 15%, 20%, or 30%.
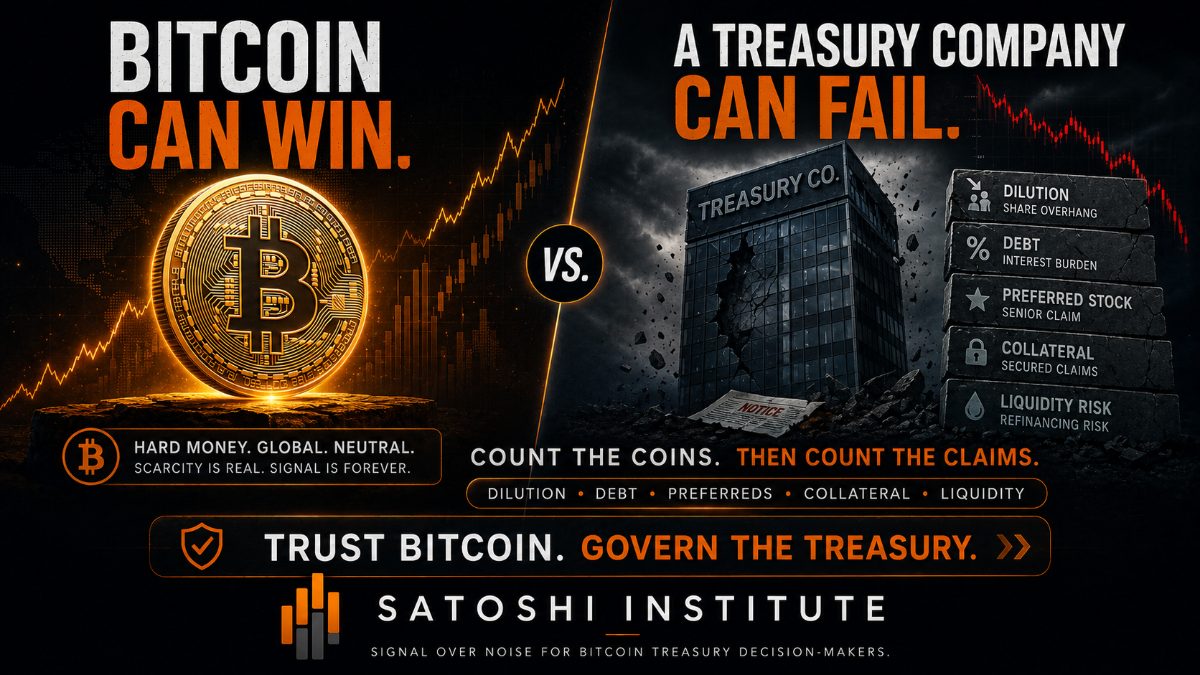
That does not automatically repair a Bitcoin treasury company.
And the market appears increasingly willing to make that distinction.
Over the past several days, Bitcoin has benefited from improving liquidity expectations, renewed demand, and the return of the debasement narrative. At the same time, investors are still questioning Bitcoin treasury companies themselves. Capital structures, dilution, valuation premiums, hedging arrangements, liquidity needs, and management decisions remain firmly attached to the wrapper.
Apparently Bitcoin did not receive the memo that a higher price was supposed to make governance optional.
It rarely does.
Signals We’re Watching
1. Bitcoin can rally while Bitcoin treasury companies remain under suspicion
The Globe and Mail highlights the growing unease surrounding companies whose primary strategy is buying and holding Bitcoin, even while Bitcoin itself has been strengthening.
That distinction matters.
Investors are increasingly asking whether owning a treasury company provides an attractive form of Bitcoin exposure or merely adds corporate governance, financing, dilution, and execution risks on top of an already volatile asset.
Treasury governance signal: A rising Bitcoin price can improve the economics of a treasury strategy. It cannot repair a weak capital structure.
2. Capital B raises another €21 million. The important number is not the Bitcoin purchase
Capital B raised approximately €21 million from institutional investors, including Adam Back and TOBAM, with the proceeds intended to support further Bitcoin accumulation.
The headline will naturally become:
More money. More Bitcoin.
Treasury v2 asks a different set of questions.
At what valuation was the capital raised?
How many new shares were issued?
What happened to Bitcoin exposure per existing share?
What happens if continued accumulation requires another financing round?
The ability to raise capital is a strategic advantage. But capital is not free simply because the proceeds eventually become Bitcoin.
Treasury governance signal: Measure accumulation against the financing used to create it.
3. PowerCompute provides a reminder that treasury engineering can become treasury risk
CryptoSlate reports that PowerCompute added approximately $3.765 million of debt following an early reset involving a Bitcoin collar tied to 307 BTC.
This is exactly the kind of story that gets lost when everyone is counting coins.
A treasury may own Bitcoin while simultaneously creating contractual claims, collateral obligations, hedges, debt service requirements, reset provisions, or other financial structures around those coins.
The Bitcoin remains scarce.
The claims against the company do not have to be.
Treasury governance signal: The more financial engineering surrounding the Bitcoin, the more important the downside mechanics become.
4. Metaplanet's U.S. ambitions revive the question of what the wrapper is actually worth
Metaplanet continues expanding its Bitcoin treasury model, including plans connected to the U.S. market. At the same time, valuation analysis cited by Yahoo Finance suggests the shares may trade materially above estimates of underlying value.
This is not necessarily evidence that the strategy is wrong.
It is evidence that investors should distinguish between:
Bitcoin value
and
the premium investors are willing to pay for management's ability to create additional Bitcoin exposure per share.
Those are very different assets.
A premium can be valuable strategic currency when management uses it intelligently.
It can also disappear.
Treasury governance signal: mNAV is not merely a valuation statistic. It is part of the treasury financing system.
5. Strategy may be preparing to buy again. The more interesting development happened before the purchase
Michael Saylor has again hinted that Strategy may resume Bitcoin accumulation.
That will generate attention.
But Strategy's more consequential recent move may have been building substantial dollar liquidity before returning to the market.
That is a different philosophy from simply converting every available dollar into Bitcoin.
It recognizes that a leveraged Bitcoin treasury requires something Bitcoin cannot provide during a drawdown:
dollar liquidity.
The largest Bitcoin treasury company appears increasingly focused not only on accumulating Bitcoin, but on preserving the capital structure that allows it to keep doing so.
That is worth watching.
Treasury governance signal: Accumulation capacity depends on liquidity capacity.
What This Actually Means
A useful separation is emerging in the market.
Bitcoin risk and Bitcoin treasury-company risk are not the same thing.
A treasury company adds another layer between the investor and the asset:
capital structure, management, governance, liquidity, financing, dilution, hedging, custody, disclosure, and execution.
When Bitcoin rises, those risks can become easier to ignore because everything looks better.
That is precisely when they should be examined.
Consider two companies that each announce a 1,000 BTC acquisition.
Company A finances the purchase using equity issued at a substantial premium, while preserving liquidity and increasing Bitcoin per share.
Company B finances the same purchase through expensive debt, collateralizes existing Bitcoin, and introduces restrictive terms that become dangerous during a drawdown.
The headline is identical:
Company buys 1,000 BTC.
The treasury outcome is not remotely identical.
That is why simply ranking treasury companies by Bitcoin holdings is becoming less informative.
The next generation of analysis must examine the structure supporting those holdings.
The Satoshi Institute Takeaway
The market may finally be learning one of the most important lessons of the Bitcoin treasury era:
Bitcoin can succeed while a Bitcoin treasury company fails.
That is not an argument against Bitcoin treasury strategies.
It is the argument for governing them.
Treasury v1 asked:
How much Bitcoin did they buy?
Treasury v2 asks:
What did shareholders give up, what obligations were created, and can the structure survive when Bitcoin stops cooperating?
Those questions will become considerably more important as Bitcoin treasury companies mature from accumulation stories into permanent financial institutions.
Trust Bitcoin. Govern the Treasury.