A Bitcoin Treasury Is Not a Substitute for a Business
A Bitcoin Treasury Is Not a Substitute for a Business
Daily Setup / Perspective
The Bitcoin treasury trade keeps becoming more institutional.
And, occasionally, considerably less so.
Strategy is now appearing among some of the largest U.S. equity issuers. Strive is talking openly about becoming the second-largest public Bitcoin holder. Capital B continues tapping investors for additional accumulation. Genius Group is attempting to rebuild a Bitcoin treasury after previously selling its holdings.
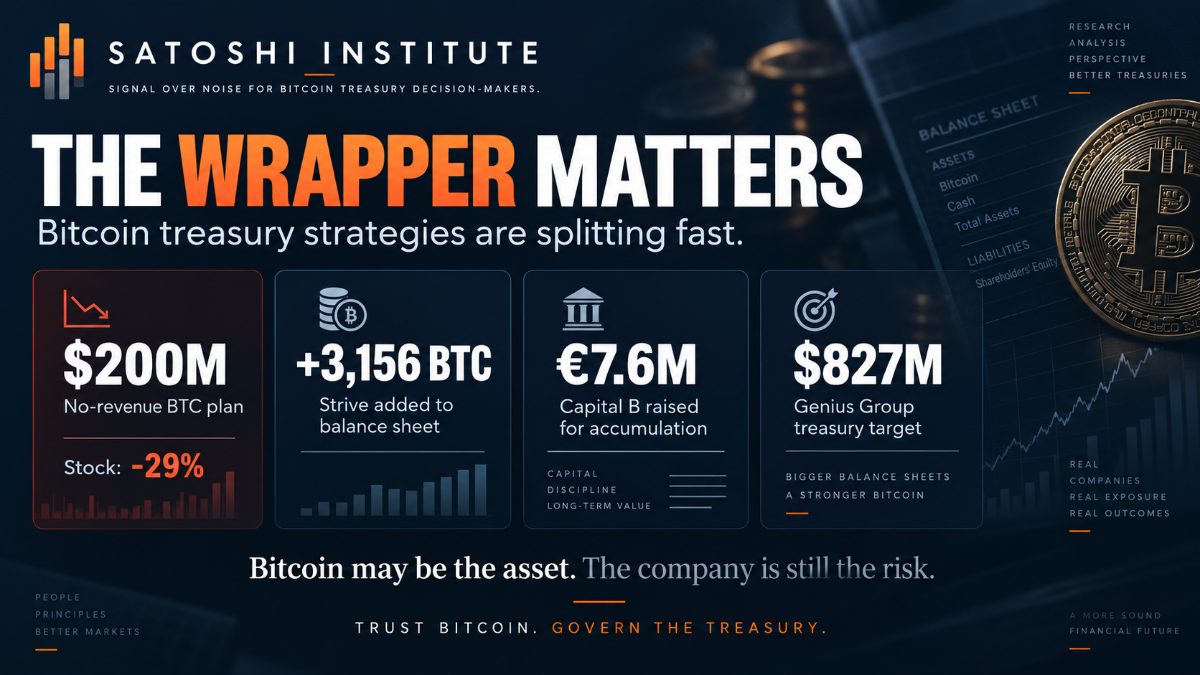
Meanwhile, another Nasdaq-listed company reportedly saw its shares fall 29% after announcing a proposed $200 million Bitcoin treasury strategy despite having no revenue.
That contrast may tell us more about where the sector is heading than Bitcoin’s price.
The first generation of treasury companies demonstrated that corporations could hold Bitcoin.
The next test is harder:
Does Bitcoin strengthen the enterprise, or has Bitcoin become the enterprise because there was not much enterprise to begin with?
Signals We Are Watching
1. A company with no revenue proposes a $200 million Bitcoin treasury
One of the most useful stories in today’s set concerns a company reportedly pursuing a $200 million Bitcoin treasury transaction despite having no revenue, followed by a roughly 29% stock decline after the announcement.
Forget, for a moment, whether Bitcoin rises.
The governance question comes first:
What economic enterprise is the treasury supporting?
Treasury assets ordinarily exist to support the obligations, liquidity requirements and strategic objectives of an operating company.
When the treasury strategy overwhelms the underlying business, investors are no longer primarily evaluating a corporation with Bitcoin. They are evaluating a capital-markets wrapper around Bitcoin. There is nothing inherently illegitimate about that model. But it should be analyzed honestly.
Governance signal
The more economically insignificant the operating business becomes, the less useful traditional corporate language becomes for describing the investment.
Boards should be explicit about whether Bitcoin is:
supporting the business
or whether
the business now exists primarily to support the Bitcoin strategy.
Those are different fiduciary propositions.
2. Strategy increasingly looks like a capital-markets institution
Recent reporting places Strategy among major U.S. equity issuers alongside some of the largest corporate capital raisers. That is a remarkable evolution. Strategy is no longer simply a software company that owns an unusually large amount of Bitcoin.
Its ability to issue common equity, preferred securities and other instruments has become central to the treasury model itself. That is why copying Strategy is more difficult than copying the visible portion of its playbook.
The visible part is:
Raise capital → buy Bitcoin.
The harder part is everything required to keep investors funding that cycle:
- market liquidity,
- security design,
- investor demand,
- balance-sheet capacity,
- governance,
- capital allocation,
- and credibility.
Governance signal
Strategy’s competitive advantage is increasingly capital access, not merely Bitcoin conviction.
A company without that machinery is not replicating Strategy by announcing a Bitcoin treasury.
It is replicating the last step.
3. Strive wants to become number two
Strive’s CEO reportedly believes the company could finish 2026 as the second-largest public Bitcoin holder, after adding 3,156 BTC to its balance sheet during the recent accumulation period.
That is an ambitious objective.
Treasury v1 will naturally track the leaderboard.
Treasury v2 should track something else alongside it:
What does each additional Bitcoin cost the existing shareholder?
If growth is financed through warrants, preferred securities, common equity or other instruments, gross BTC accumulation tells only half the story.
The other half sits in the denominator and the capital stack.
Governance signal
There are at least two ways to become a larger Bitcoin treasury:
Own more Bitcoin.
Or create more claims against a company that owns more Bitcoin.
The institutional analysis needs both numbers.
4. Capital B continues raising to accumulate
Capital B reportedly raised another €7.6 million from investors, including Adam Back, to finance continued Bitcoin accumulation.
This follows earlier fundraising activity and illustrates the recurring nature of the treasury financing model.
The significant question is not whether Capital B can raise another round.
It is whether each round improves the economic position of the existing shareholder after accounting for:
- new shares,
- issuance price,
- Bitcoin acquired,
- treasury value,
- and any change in per-share exposure.
Governance signal
A successful financing is not automatically a successful treasury transaction.
The relevant question is:
Did the capital raised create more economic Bitcoin exposure than the shareholder claims issued to obtain it?
That should become a standard treasury test.
5. Genius Group demonstrates why the funding structure matters
Genius Group reportedly wants to rebuild a Bitcoin treasury worth as much as $827 million after previously selling its Bitcoin holdings. Its broader capital plan reportedly also contemplates a substantial AI portfolio. The interesting part is not the ambition. It is what happened before it.
The company already demonstrated that corporate circumstances can override a Bitcoin-holding objective. Now it is attempting to construct financing structures that allow the strategy to resume. That is a real-world demonstration of a point the market often prefers to ignore:
Corporate Bitcoin is conditional Bitcoin.
A company does not simply need sufficient conviction to acquire Bitcoin. It needs sufficient financial architecture to keep it.
Governance signal
The quality of the treasury cannot be separated from the durability of its funding.
What This Actually Means
The Bitcoin treasury sector is moving toward a fork. On one side are companies becoming sophisticated capital allocators.
- They are designing preferred securities.
- Managing liquidity.
- Issuing equity.
- Repurchasing securities.
- Managing dilution.
- Optimizing financing costs.
- Building investor bases.
- And using those capabilities to acquire Bitcoin.
On the other side are companies for which:
“We are becoming a Bitcoin treasury company”
risks becoming the entire corporate strategy.
Those two groups should not receive the same analytical treatment. A Bitcoin treasury can be an asset-allocation strategy. It can also be a financing strategy. It can become a capital-markets strategy. And at the extreme, it can become a substitute for an operating strategy.
That final transition deserves considerably more scrutiny. Because Bitcoin can strengthen a good balance sheet. It cannot manufacture operating economics that were never there.