Strategy now has cash for defense and cash for offense
Strategy now has cash for defense and cash for offense
Daily Perspective
Bitcoin just had its best week in years. Spot ETFs pulled in roughly $1.9 billion. BlackRock alone accounted for about $1.3 billion of that demand.
Cue the victory laps.
But Strategy did something more interesting than buy into the rally.
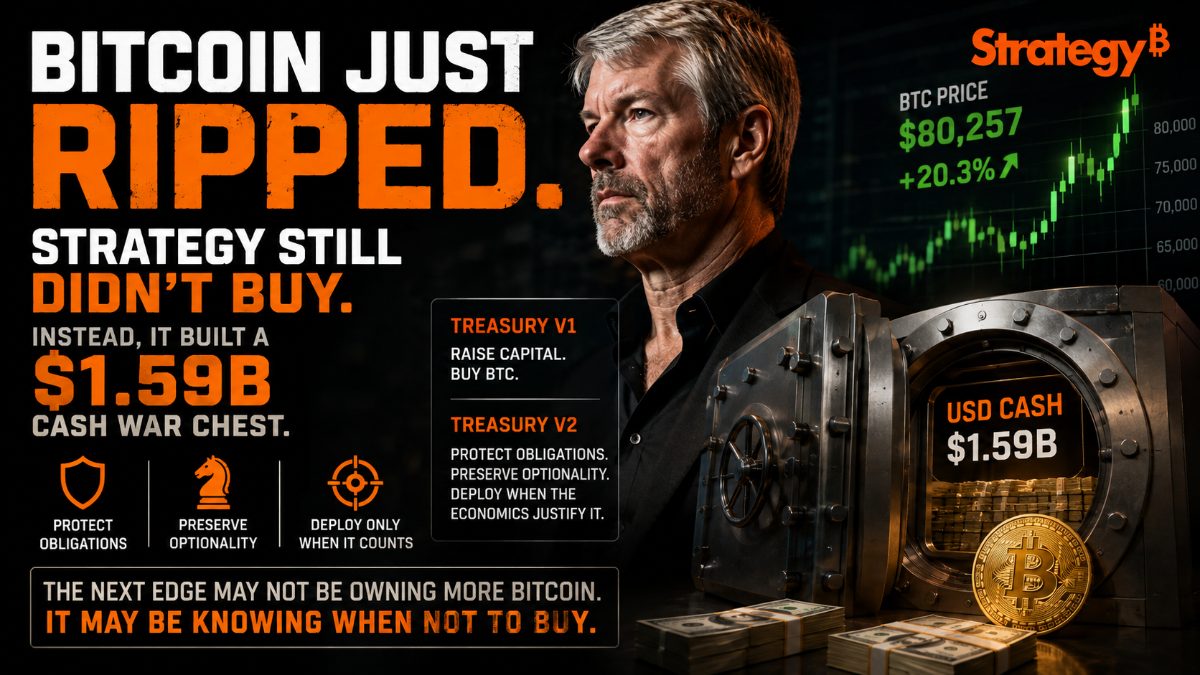
It did not buy Bitcoin at all.
Instead, it created a separate $1.59 billion pool of unrestricted USD liquidity. Combined with its restricted reserve, Strategy now holds roughly $6.69 billion in designated dollar liquidity.
That may tell us more about where Bitcoin treasury management is going than another billion-dollar BTC purchase would have.
Signals We’re Watching
Strategy has separated defense from offense
Strategy now appears to have two distinct liquidity pools.
Its restricted USD Reserve covers preferred dividends and debt interest. The new USD Cash pool can reportedly be deployed more flexibly for Bitcoin purchases, preferred securities, convertible management, reserve additions, and other capital actions.
That distinction matters.
A treasury should not force the same dollar to serve simultaneously as emergency liquidity, dividend coverage, collateral protection, and opportunistic investment capital.
Strategy is beginning to separate those functions.
That looks considerably more like institutional treasury management than "raise money, buy Bitcoin."
The new cash came with dilution
There is another side to the story.
Strategy reportedly sold 18.26 million Class A shares and raised roughly $2.01 billion in net proceeds.
Some funded preferred repurchases. Some increased reserves. The remainder created the new cash pool.
So shareholders received more liquidity and optionality.
They also received more shares.
That means the proper performance question is not simply whether Strategy now has $6.69 billion available.
It is whether the capital raised creates more value per existing share than the dilution required to raise it.
Liquidity has value.
So does the denominator.
ETF demand came roaring back, but the year is still negative
U.S. spot Bitcoin ETFs reportedly attracted about $1.92 billion last week, their strongest week in ten months. Bitcoin itself gained roughly 23%.
That sounds decisive until you zoom out.
The funds remain approximately $2.9 billion in net outflows for 2026.
One strong week does not erase months of withdrawals.
For treasury boards, the lesson is useful. Capital flows can reverse quickly in both directions. Building a treasury around the assumption that institutional demand will always be present is simply another form of price dependence.
Markets are generous right up until they are not.
High bond yields still sit underneath the rally
Long-term government borrowing costs remain elevated. The 30-year U.S. Treasury yield has recently traded above 5.3%, with long-duration yields elevated across several major economies.
At the same time, expanded Treasury debt buybacks have helped ease some market pressure.
That leaves Bitcoin treasury companies operating in a strange environment.
Liquidity conditions can improve enough to ignite a rally while the underlying cost of capital remains historically expensive.
That means management cannot treat a rising BTC price as evidence that financing risk disappeared.
Price can move faster than the balance sheet.
Chaince shows the other side of capital flexibility
Chaince Digital reportedly wants shareholders to authorize as many as 20 billion ordinary shares while also considering reverse splits after launching a $300 million stock offering.
That is capital flexibility taken to its logical extreme.
A large authorized share pool gives management financing options.
It also gives shareholders enormous dilution exposure.
The governance question is therefore not whether management can issue shares.
It is what limits exist on when, why, and at what economics those shares will be issued.
"Authorized" is not the same as "responsible."
What This Actually Means
Strategy's new cash pool may represent a meaningful evolution. The original treasury model optimized for one action: acquire more Bitcoin.
The newer model needs optionality.
- Buy Bitcoin when economics favor it.
- Repurchase securities when they trade cheaply.
- Protect dividend coverage.
- Manage convertibles.
- Preserve liquidity when capital markets deteriorate.
That is a much more sophisticated capital-allocation system.
But sophistication creates its own governance requirement.
Once management has billions of dollars that can move between Bitcoin, securities, reserves, and liabilities, shareholders need to know the rules governing those choices.
A war chest without an allocation policy is simply a very large discretionary account.